The issue with per-validator assignment and incentives
Let us assume that some value can be extracted from the includer role, following the arguments presented in my previous reply. This does not necessarily require explicit protocol rewards as it is possible to obtain income out of band. Even if sufficient consolidation can be sustained through individual consolidation incentives under either includer-selection mechanism, small validators would depend much more heavily on their ability to extract includer MEV with per-validator assignment.
Under per-validator assignment, each validator key is selected equally often. The small 32-ETH validator will then receive 64 times as many includer assignments per ETH as the consolidated 2048-ETH validator. The incentive needed to induce consolidation must account for the income available to an operator willing and able to extract this value. I assume here individual consolidation incentives. With collective consolidation incentives alone, an operator could retain the private benefit of keeping its validators small while sharing the cost of insufficient consolidation with everyone else, which would be highly problematic.
Some SSPs will be better equipped to extract includer MEV than others, and these can keep their validators small to enhance their yield. An incentive that induces sufficient aggregate consolidation need not outweigh this advantage for every SSP. The SSP has a choice, whereas a solo staker owning 32 ETH cannot consolidate on its own and must receive the lower consensus yield assigned to a small validator. If it simply constructs its IL from the public mempool, without negotiating payments or relying on an external service, it cannot make up the difference.
Services analogous to MEV-Boost could make includer income more accessible. But they need not put solo stakers on equal ground with an SSP keeping its validators small to own a large fraction of all includer seats. Danny Ryan once used the term “stratum for cartelization” with reference to liquid staking derivatives. Specialized IL services could provide another such stratum, and per-validator assignments could reinforce it by allowing an operator’s share of includer seats to greatly exceed its share of stake.
Insofar as small stakers obtain rewards by delegating IL construction to specialized services, their greater share of includer assignments need not translate into a corresponding diversity of independent inclusion decisions. We should therefore be careful about treating the additional assignments to smaller validators as an advantage without also considering what the small staker must do to remain competitive under the incentives needed to sustain consolidation.
Illustrating the tensions
The four figures below illustrate the issues at hand. They compare yields under baseline assumptions, and are simplified in that they do not solve for the equilibrium under competition, concentration, service adoption, entry and exit.
We model a future scenario where the consensus yield has been reduced moderately and the assumed reference staking yield for a capable SSP is 1.5% at 40M ETH staked. This includes assumed proposer MEV of 0.2% and aggregate reference includer MEV of 0.025%. The includer MEV is thus 1/8 of the proposer MEV in aggregate, and with 16 includers per slot, each includer earns around 1/128 of what the proposer earns on average per slot. The default consolidation level is 100,000 validators, corresponding to an average effective balance of 400 ETH (this is varied in Figure 3).
The reference includer income is what a capable operator can obtain, illustrated as if every includer duty earned the capable operator’s income. The consolidation incentive is here modeled as compensating validators for missed includer opportunities by raising their consensus yield. The illustrated schedule makes the reference operator indifferent between different validator balances. Any additional incentives or operational savings that would make consolidation strictly preferable are left outside the illustration. The same yields could instead be obtained by reducing the consensus yield of smaller validators from a higher baseline. The inverse-balance, validator-fee form discussed in previous research is applied.
As previously discussed, it may be difficult for solo stakers to earn as much as an SSP, which may own a large share of the includers due to keeping its ETH deconsolidated. The figures illustrate the outcome when solo stakers obtain 50% of the reference includer income per duty, with access to proposer income held equal. Proposer income is counted after any revenue diverted to includers.
In Figure 1, we first show how big the individual consolidation incentive must be in order to offset includer MEV. A 32-ETH validator will have frequent includer assignments and its total yield outside of MEV from these assignments is therefore only about 1.19%. The rest of the income needed to reach 1.5% must derive from includer MEV. If the 32-ETH solo staker is only capable of capturing half the includer MEV per duty of the most capable SSP (purple dashed line), then it will receive a lower aggregate yield than competing stakers.
Figure 1. Yield composition under per-validator selection with 100,000 validators and 40M ETH staked. The coloured areas describe the capable operator, while the dashed purple line shows total yield at 50% capture. At this capture rate, a 32-ETH validator earns about 1.34%, compared with nearly 1.50% for a 2048-ETH validator.
Figure 2 shows how a reduced ability to capture includer MEV can reduce participation among solo stakers. The rising reservation-yield curve represents the minimum yield at which prospective 32-ETH solo stakers are willing to participate, reflecting differences in costs, risks and outside options. We assume that a 32-ETH solo staker is capable of capturing half the includer MEV of the most capable SSP, both under per-validator assignment and proportional assignment. However, given that they receive far more assignments under per-validator distribution, they receive a lower yield once individual consolidation incentives are accounted for, pushing some out of solo staking.
Figure 2. A 32-ETH staker capturing 50% of reference includer income earns about 1.34% under per-validator selection (purple) and 1.49% under proportional selection (pink). The shaded interval marks prospective solo stakers who would participate under proportional selection but not under per-validator selection. The reservation-yield curve and participation axis are illustrative.
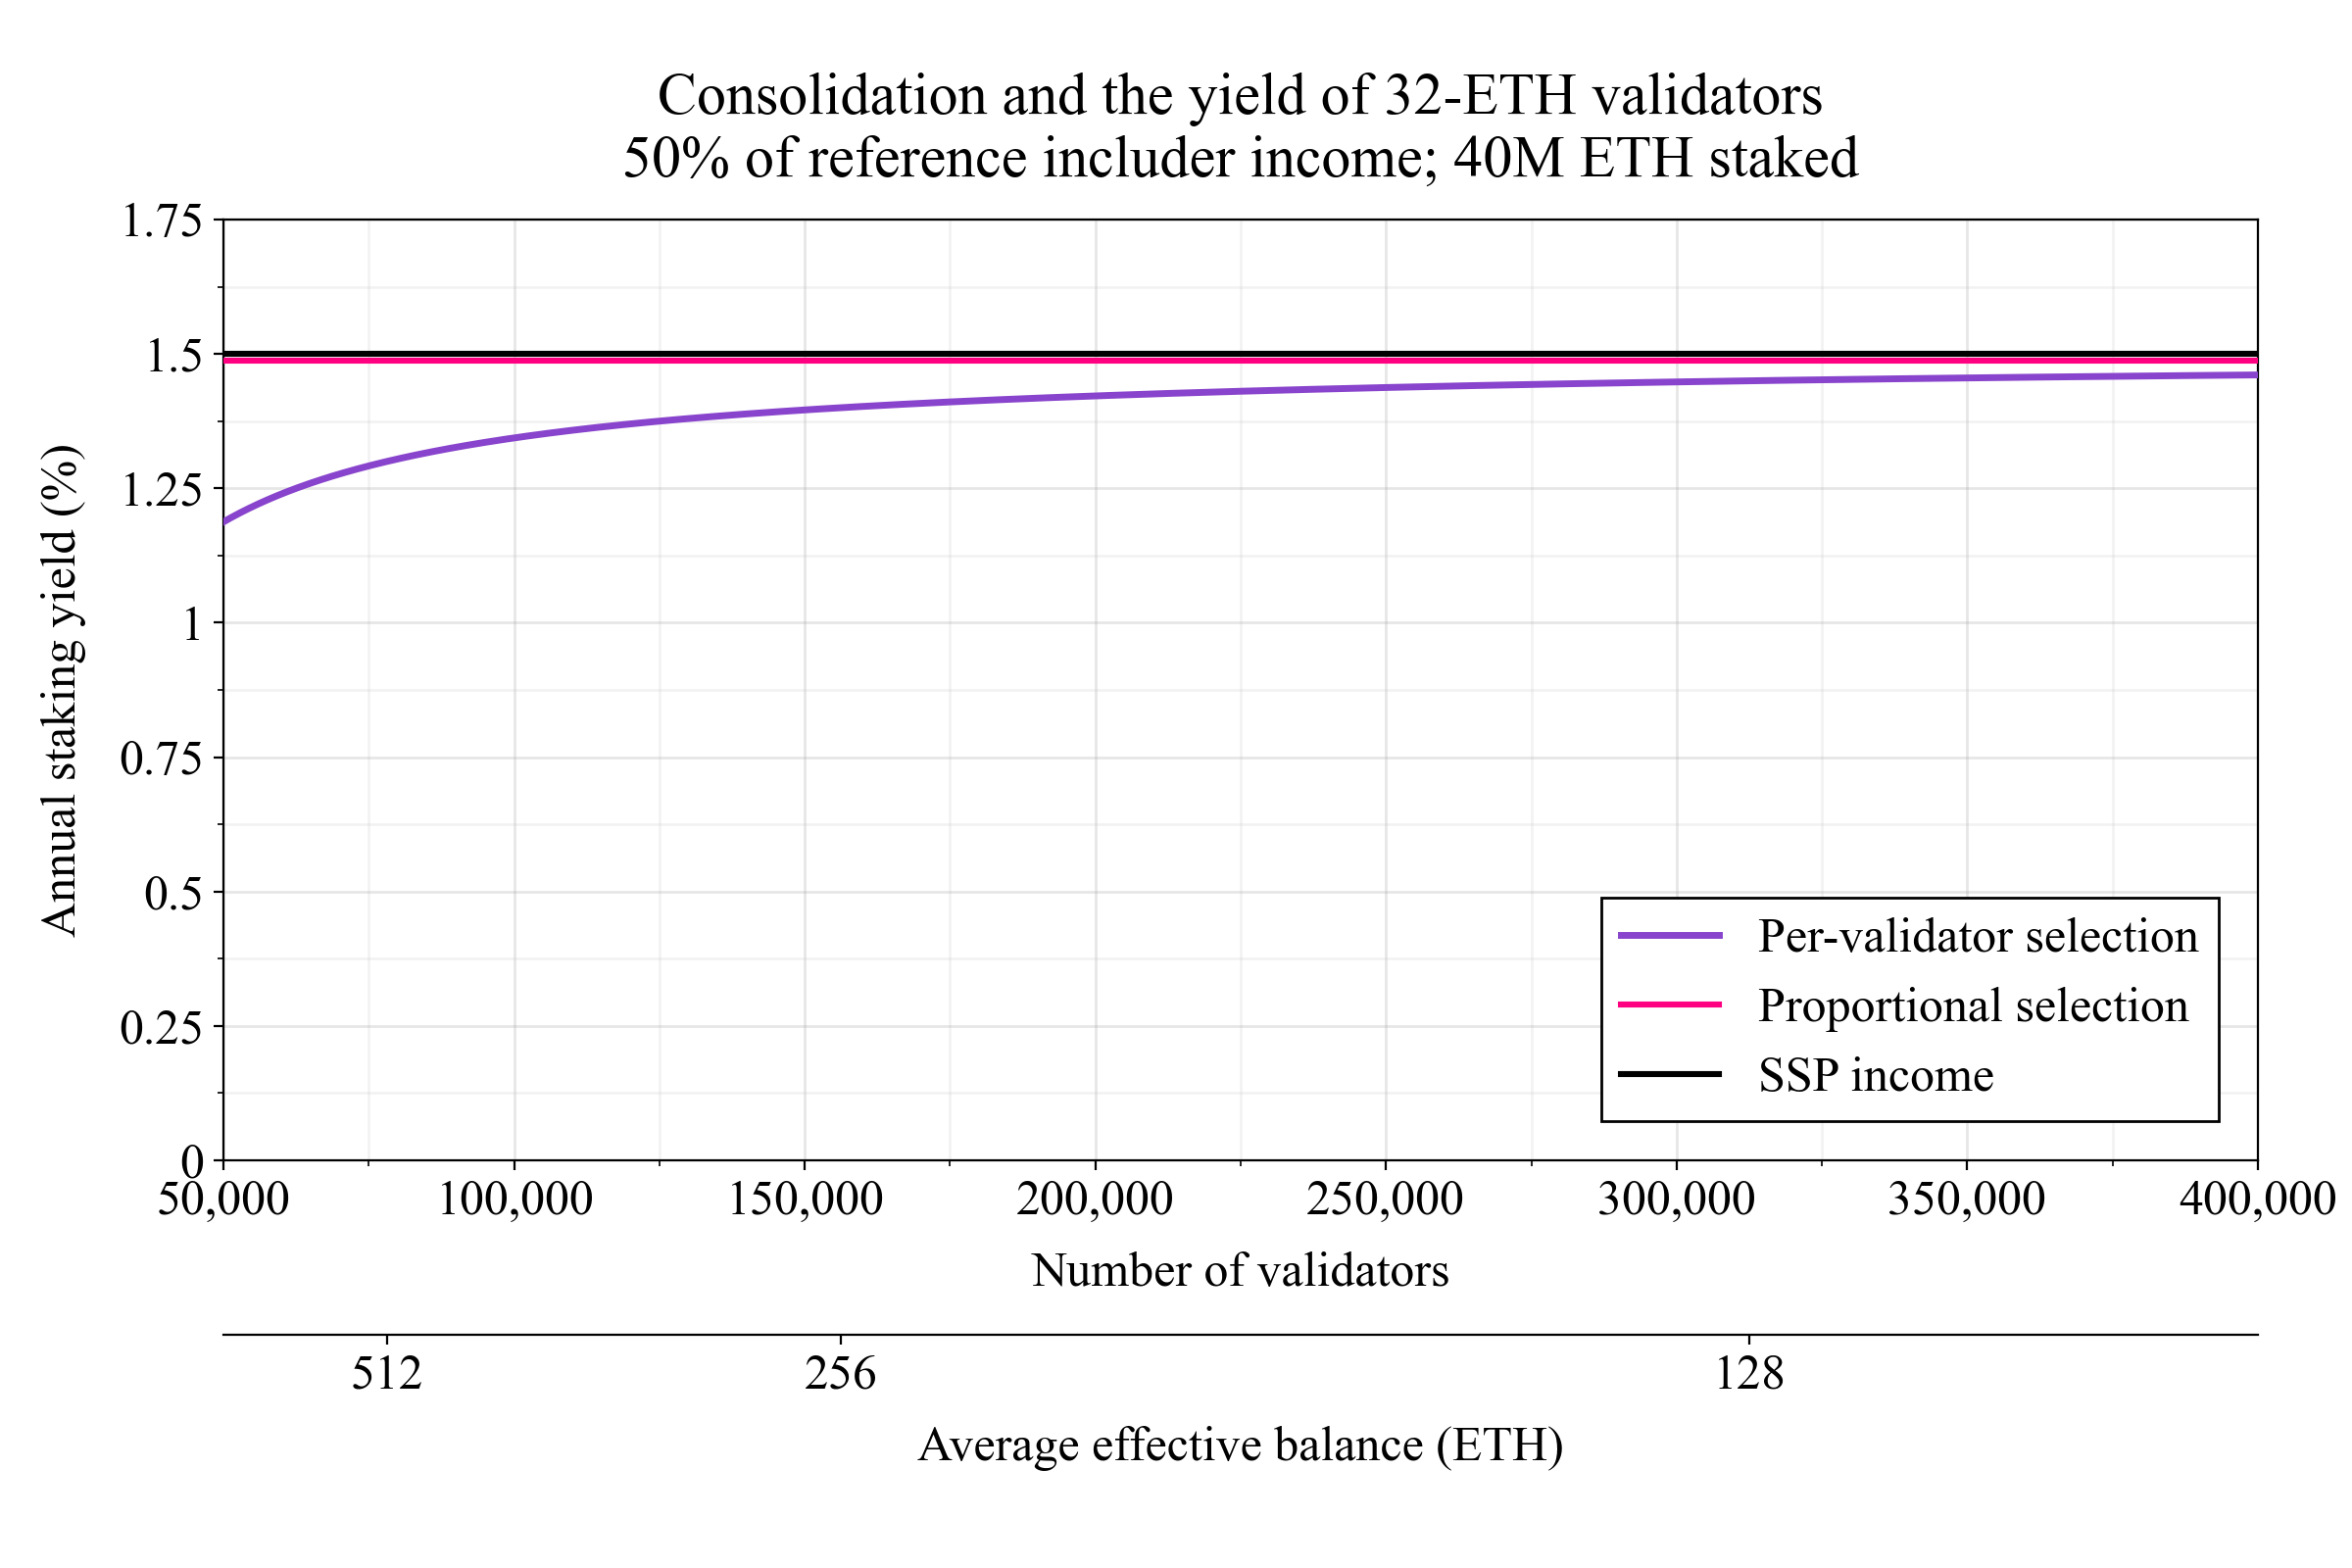
Figure 3 extends the comparison across consolidation levels. As the validator count falls, each remaining small validator receives more includer assignments, and a larger consensus-yield differential is needed to offset the capable operator’s advantage from keeping its stake split. The incentive is recalibrated at each validator count to maintain this offset.
Figure 3. With 40M ETH staked and 50% capture, the 32-ETH solo staker’s yield falls as consolidation increases under per-validator selection (purple), while proportional selection remains at about 1.49% (pink). The black line shows the capable SSP’s reference yield of 1.5%. These are comparisons across consolidation levels, rather than a prediction of how consolidation will evolve.
Figure 4 varies the assumed aggregate includer MEV, retaining 100,000 validators, 40M ETH staked and 50% capture. Consensus rewards are adjusted as includer income changes to keep the capable operator’s total yield at 1.5%, with proposer income held at 0.2%. At each point, the total consensus rewards are the same under both selection mechanisms.
Figure 4. Sensitivity to aggregate reference includer yield, from 0% to 0.1%, with the 0.025% baseline marked by the vertical dashed line. At that baseline, the solo staker’s yield is about 0.14 percentage points lower under per-validator selection than under proportional selection. Under the illustrated incentive schedule, this gap grows in proportion to includer income.
Conclusions
Per-validator assignment creates an incentive to split stake that consolidation incentives must then counteract. An SSP can weigh includer income against the consolidation incentive when choosing its validator balances. A solo staker with 32 ETH cannot make that choice: if it cannot monetize includer duties equally well, it receives a lower total yield. These solo stakers must match the extractive ability of the most capable SSP to stay competitive on yield. This may be particularly hard if that SSP comes to dominate the includer role while competing SSPs consolidate to avoid the pressure to extract includer MEV.
Under these conditions, per-validator assignment can make Ethereum less decentralized at the consensus layer. Smaller stakers may leave independent validation, while those who remain may delegate IL construction to close the yield gap. A claimed gain in decentralized transaction inclusion may therefore be paid for through weaker decentralization at the consensus layer, and may itself be undermined when inclusion decisions are outsourced.
We could therefore end up with one dedicated SSP dominating the includer role with a deconsolidated validator set, while 32-ETH solo staking offers a lower yield than both operators that specialize in includer MEV and those that consolidate to reduce their dependence on it. This would weaken Ethereum’s censorship resistance and decentralization.